A coworking feasibility study answers the question sitting underneath the lease: whether there is enough demand in this catchment, at the price this market pays, to fill this specific square footage and still make money. Not an industry outlook. Your building, your trade area, your numbers.
Talk through your buildingIn every one of those cases the same thing is already true: the building has an answer. The feasibility study exists to find that answer before the capital is committed rather than after.
Who is actually inside the trade area. Population, employment mix, business formation and remote-work density for the specific radius that will drive this location, pulled from Census and demographic sources, then benchmarked rather than merely described.
Every operator already serving that catchment, what they charge, what they are missing, and where their occupancy suggests strain. A market can be underserved and still be the wrong market if the wrong competitor is entrenched in it.
A rate for every sellable unit, grounded in comparable spaces rather than round numbers, and confidence-rated so you can see which prices are well supported by the market and which are a judgment call.
How the square footage becomes inventory: office count and mix, meeting rooms, open desks, support and circulation. This is where a floor plan turns into a rent roll, and where optimistic models quietly break.
Revenue by stream, a real operating expense build, a month-by-month fill curve, break-even and CapEx payback. The same model a lender or an investment committee would want to interrogate line by line.
Whether this building supports the business, what would have to be true for it to work, and where the plan is most exposed. A study that cannot arrive at no is marketing.
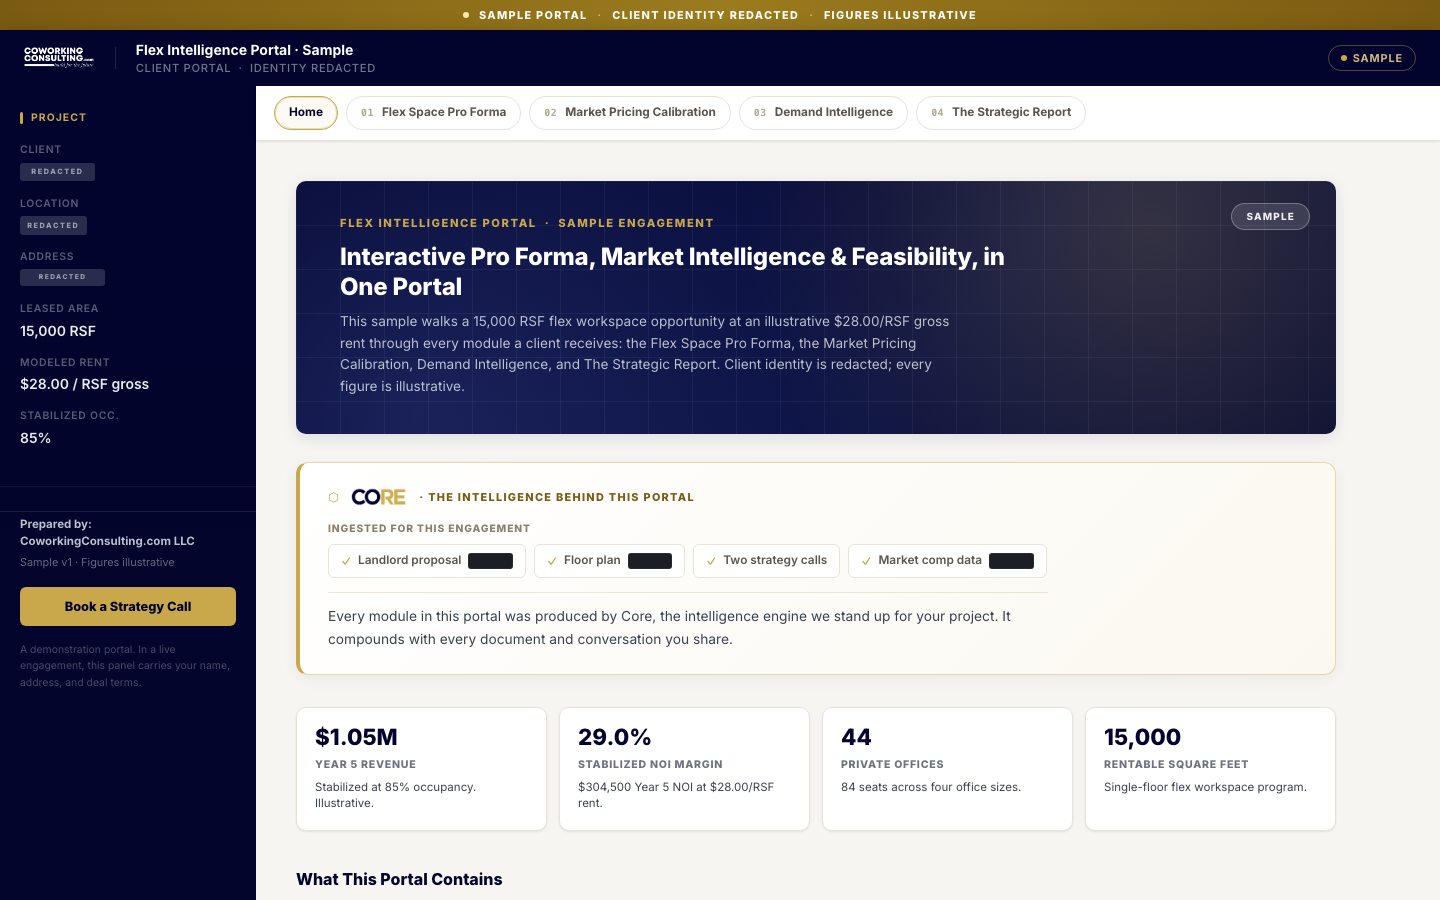
A five-year statement built on your building: every revenue line, every operating cost, and the year the space starts earning. In the example below revenue runs from $407,188 to $988,645 across six income lines, and the full expense block and net operating income sit beneath it.

Pro forma
Tells you what happens if the space fills.
It takes a set of assumptions about your building and turns them into a financial model: what it earns, what it costs to run, when it breaks even. The right instrument when the lease economics are settled and the question is mostly the math.
Feasibility study
Tells you whether it fills.
It puts the market underneath those assumptions. Whether the demand exists to fill the space at all, who else is competing for it, and what the market will genuinely pay. The right instrument when the question is still whether this location is the right location.
Both run on the same engine, so the pro forma extends into the study without starting over.
See the Flex Space Pro FormaThe full financial model with the working spreadsheet behind it, so every number can be traced back to the assumption that produced it.
Demand analysis and pricing research with their sourcing visible, including where confidence is high and where it is a judgment call.
Space allocation set against the actual floor plan, so the unit mix is something you can see rather than a table you have to trust.
A feasibility study is not read once. It gets revisited when lease terms move, when the test fit changes, when a partner or a lender asks a question nobody anticipated. A static report cannot answer a question it was not written for.
The fastest way to know what this needs is a conversation about the specific space: what the lease says, what the floor plan allows, and what the market around it will support.
Scope & Pricing
Prefer to talk first? Book a call instead.