I have my pro forma. Now what?
Year one is negative. Occupancy never reaches 100 percent. The number everyone points at is not revenue. Eleven stops through the spreadsheet, block by block.
Every pro forma is built to one building
Every figure in the screenshots on this page belongs to a single property: its square footage, its floor plan, its test fit, its market. The unit mix is a recommendation made for that building, never a template. How many offices of each size a floor plate should hold, what each should rent for, how area divides between private rooms, desks and amenity space, and what the local market will actually carry are decided per property, and they move with the plate, the market and the operator.
Your model will carry its own counts, its own sizes, its own rates and its own allocation. Read these screenshots for the structure and the logic. The numbers are illustrative sample data, not a client deal and not a benchmark.
Blue cells are yours. Black cells are derived.
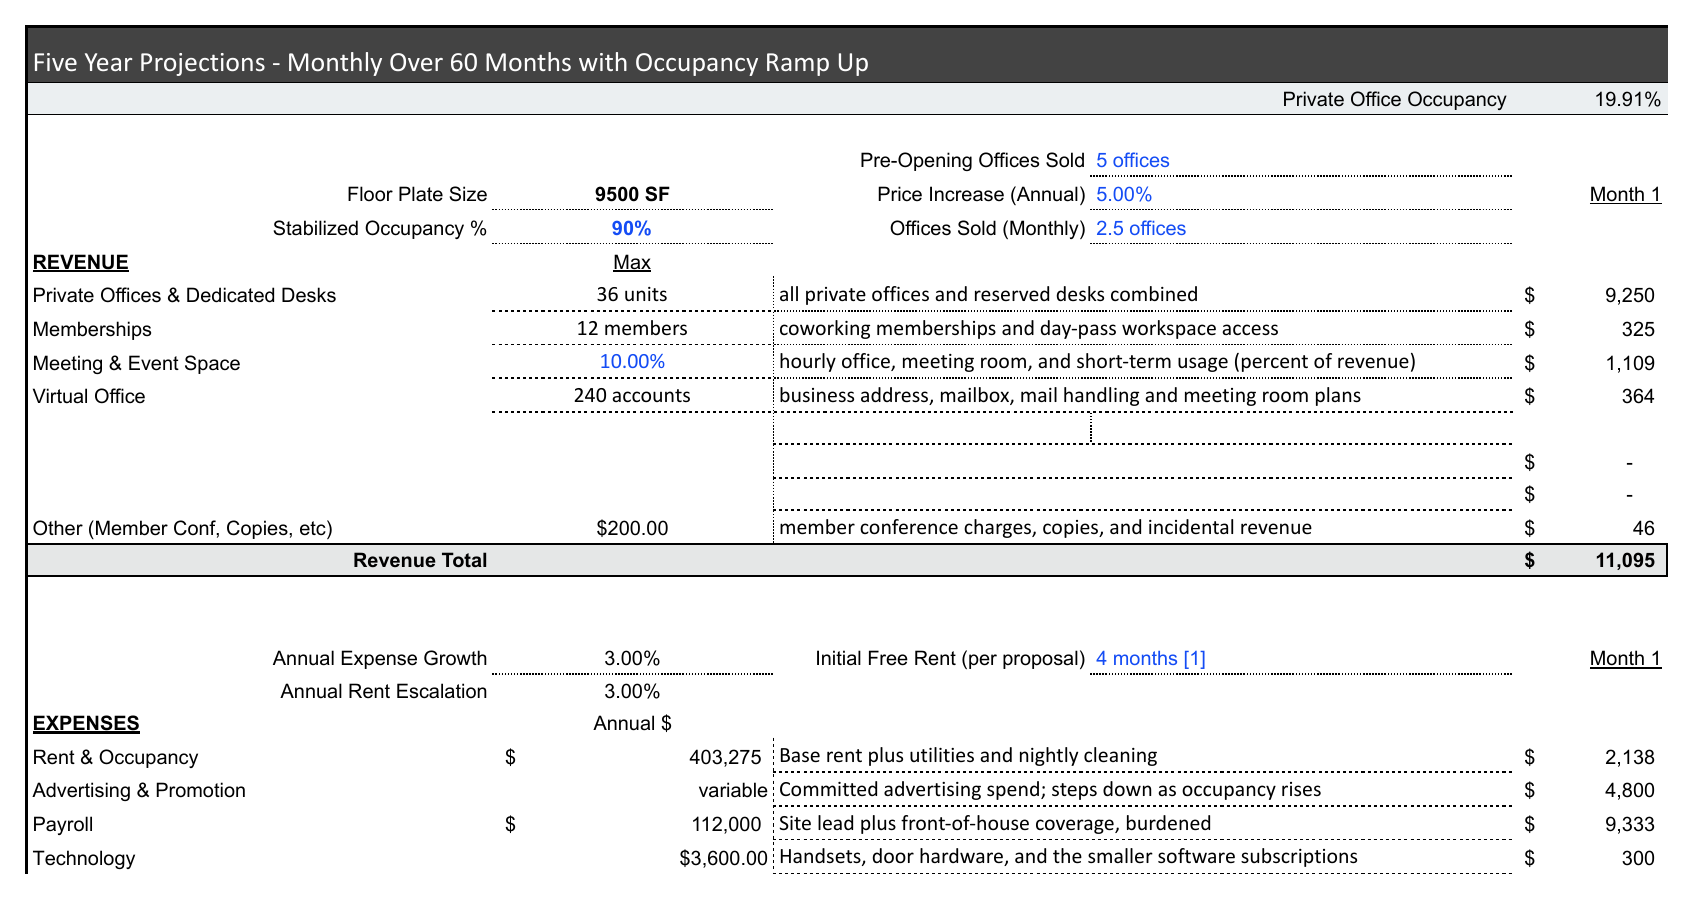
Open the Google Sheet and this is the fastest thing to know. Any figure in blue is an input you can change: stabilized occupancy, offices sold per month, pre-opening offices sold, the annual price increase, the free rent period. Everything in black is computed from those, so it moves on its own and is not meant to be typed over.
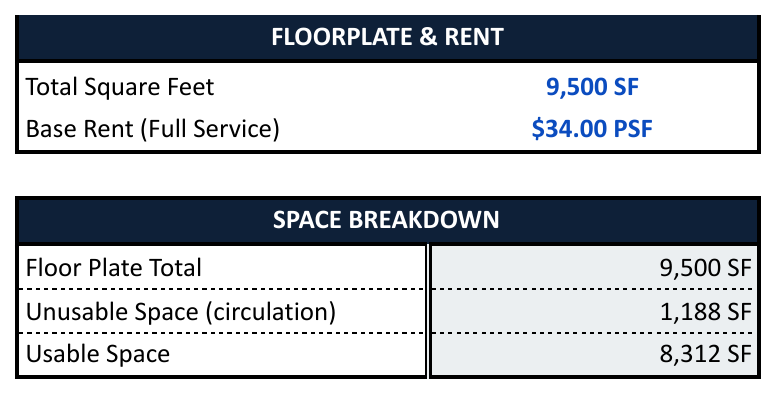
That convention is what makes the model testable in front of you. Change a blue cell and watch the black ones respond. It is also the practical form of the documented, benchmarked, and assumed distinction below: blue is where judgment lives, black is arithmetic.
Where each number comes from
Every figure in the model belongs to one of three categories, and knowing which one you are looking at changes how hard you should push on it.
| Category | Where it comes from | Typical examples |
|---|---|---|
| Documented | A source document you can point at | Base rent, abatement, escalation, term, rentable square footage, tenant improvement allowance |
| Benchmarked | Calibrated operating data across comparable locations, or surveyed local market evidence | The occupancy ramp, expense ratios, recommended rates and the comparable band behind them |
| Assumed | A judgment made where no source exists, stated as such | Office sizes on an unlabeled plan, ancillary membership counts, event volume, construction duration |
An assumption is not a flaw. An assumption presented as a fact is. Each one is labeled where it appears, so the difference is visible without having to ask.
Reading a pro forma like a pro
Eleven stops through the model, in the order a practiced reader takes them. Each one shows the block, says where to put your eye, and names what would worry me if I saw it in yours.
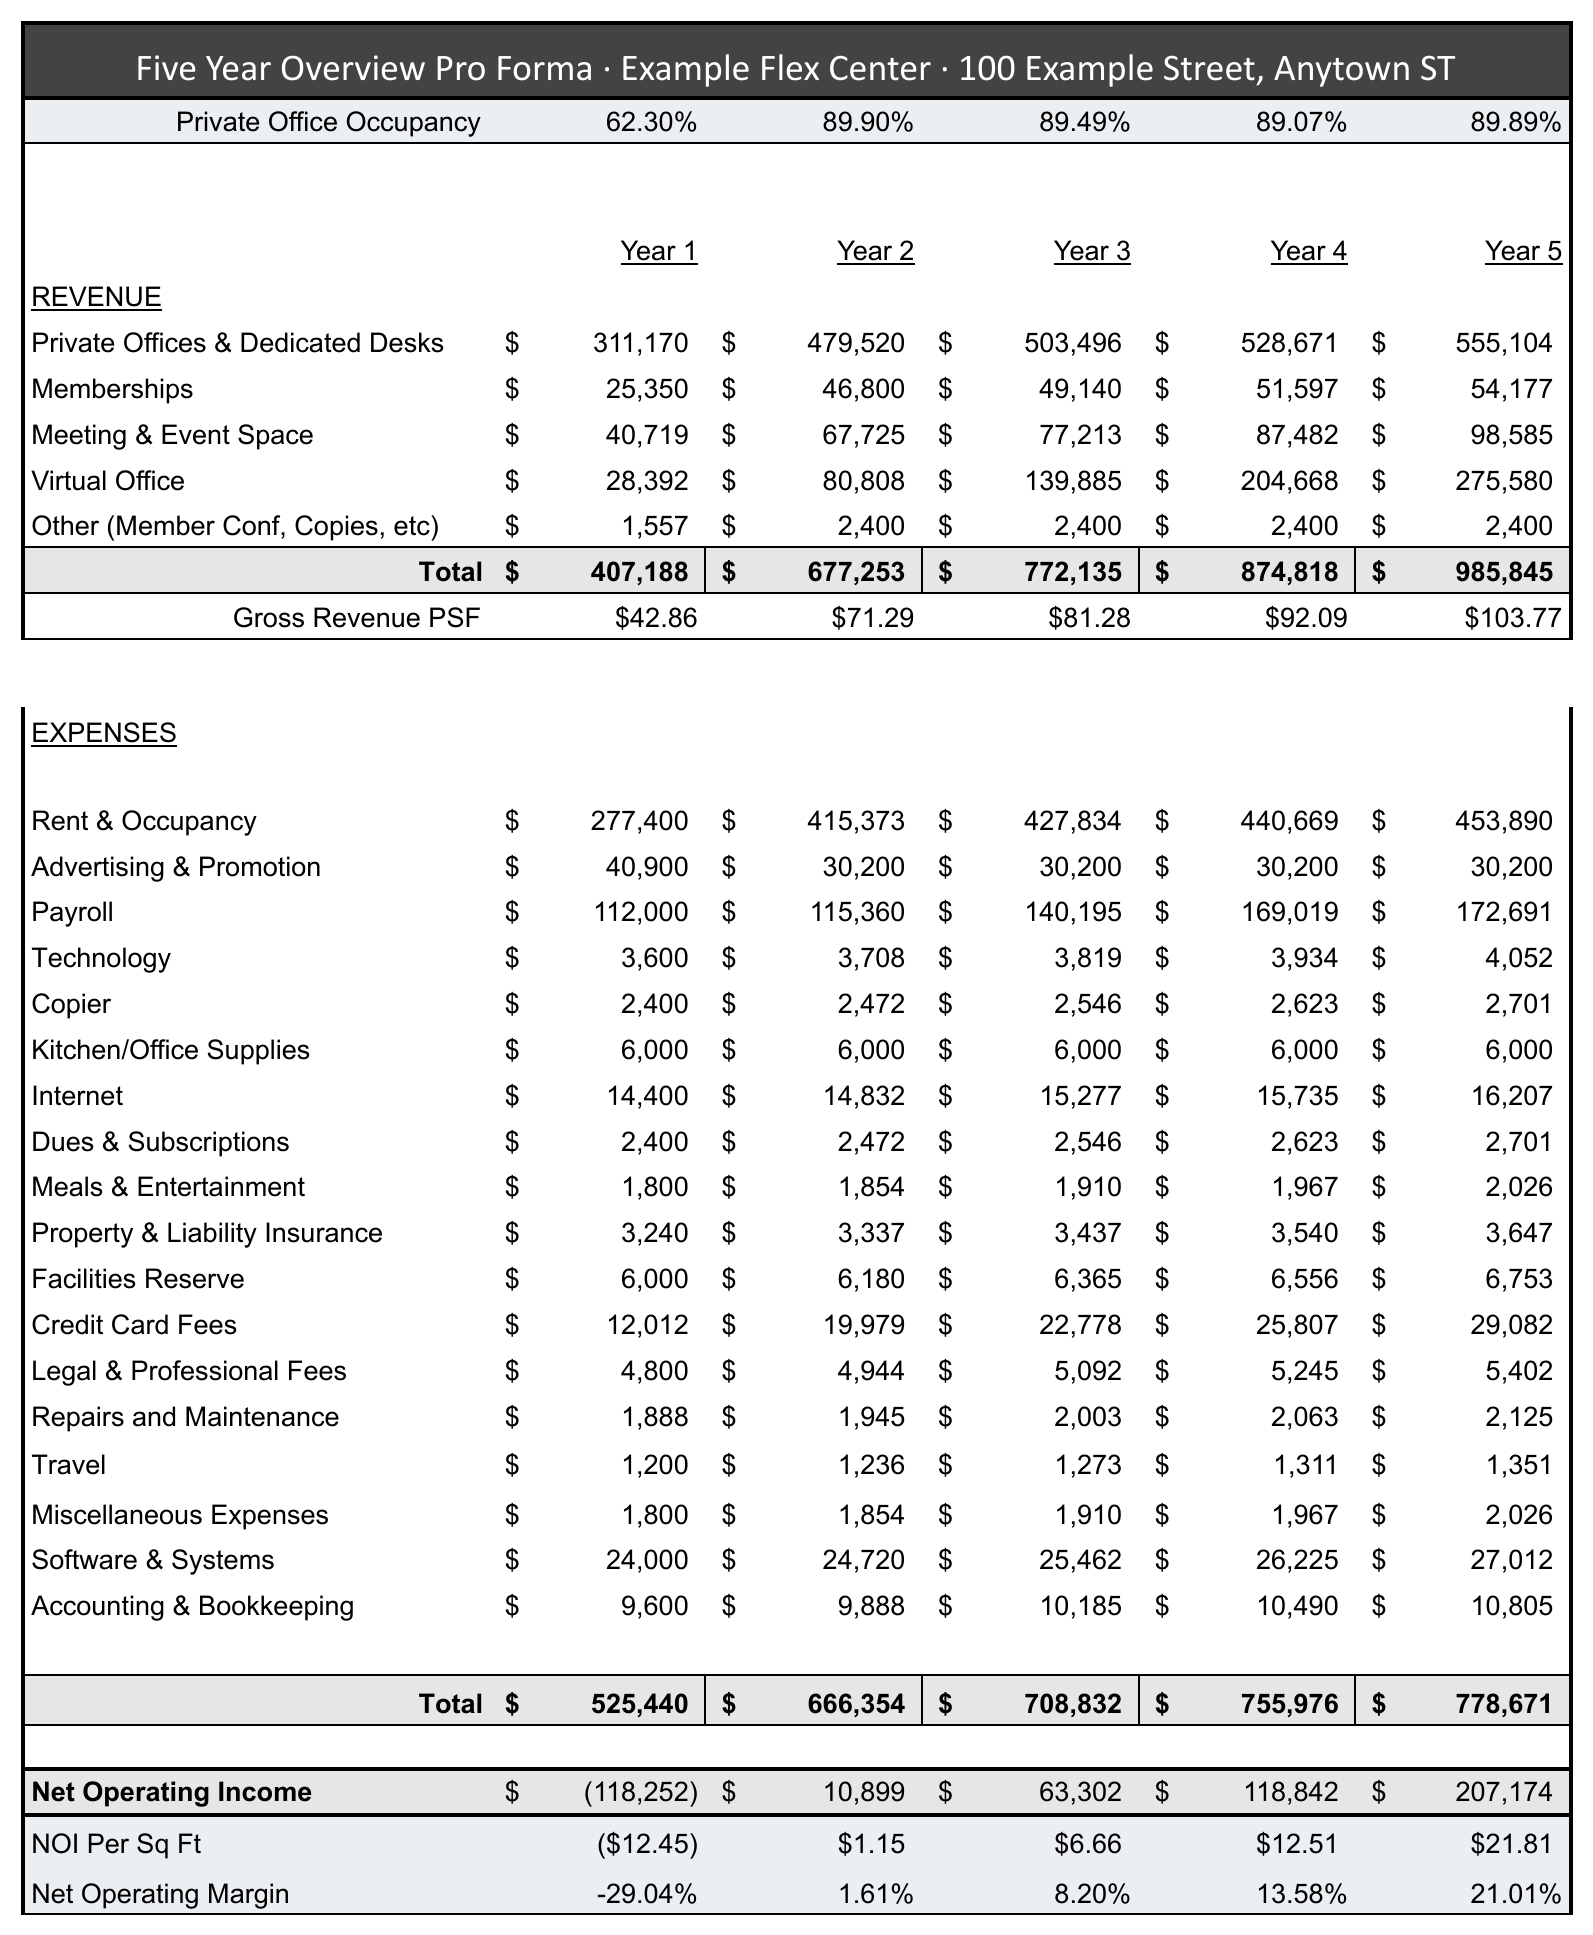
Start with the basics
A pro forma is a decision instrument, not a prediction. Start where every other number comes from.
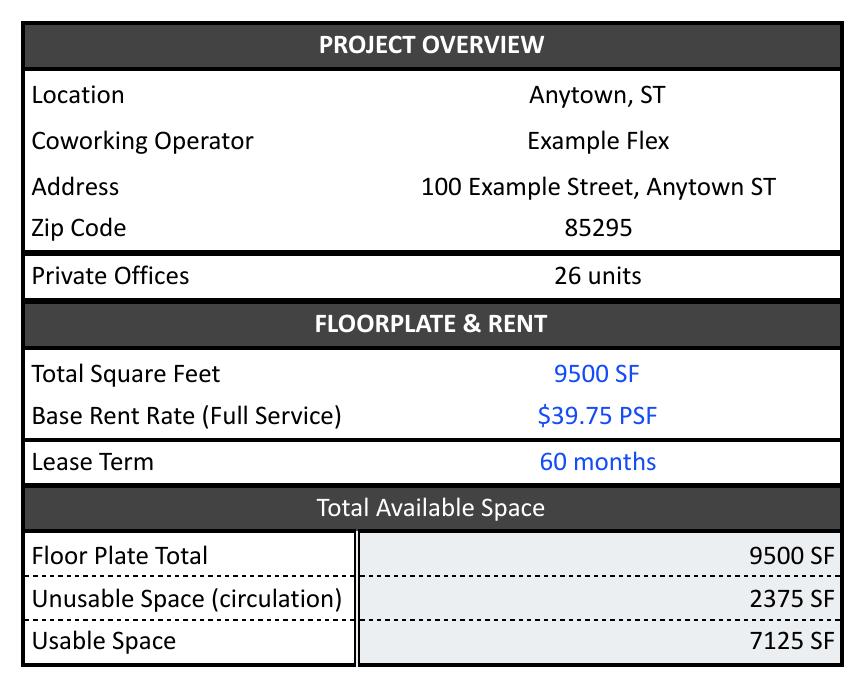
What to look at
The address, the rentable square footage, the rent rate and whether it is gross or net, the abatement period, the lease term, and the office count. Six numbers, thirty seconds.
What would worry me
Any one not matching your building or your proposal. Wrong square footage or wrong rent is not a small error, it is a model of a different deal. Cheapest check here, most often skipped.
See what the space holds
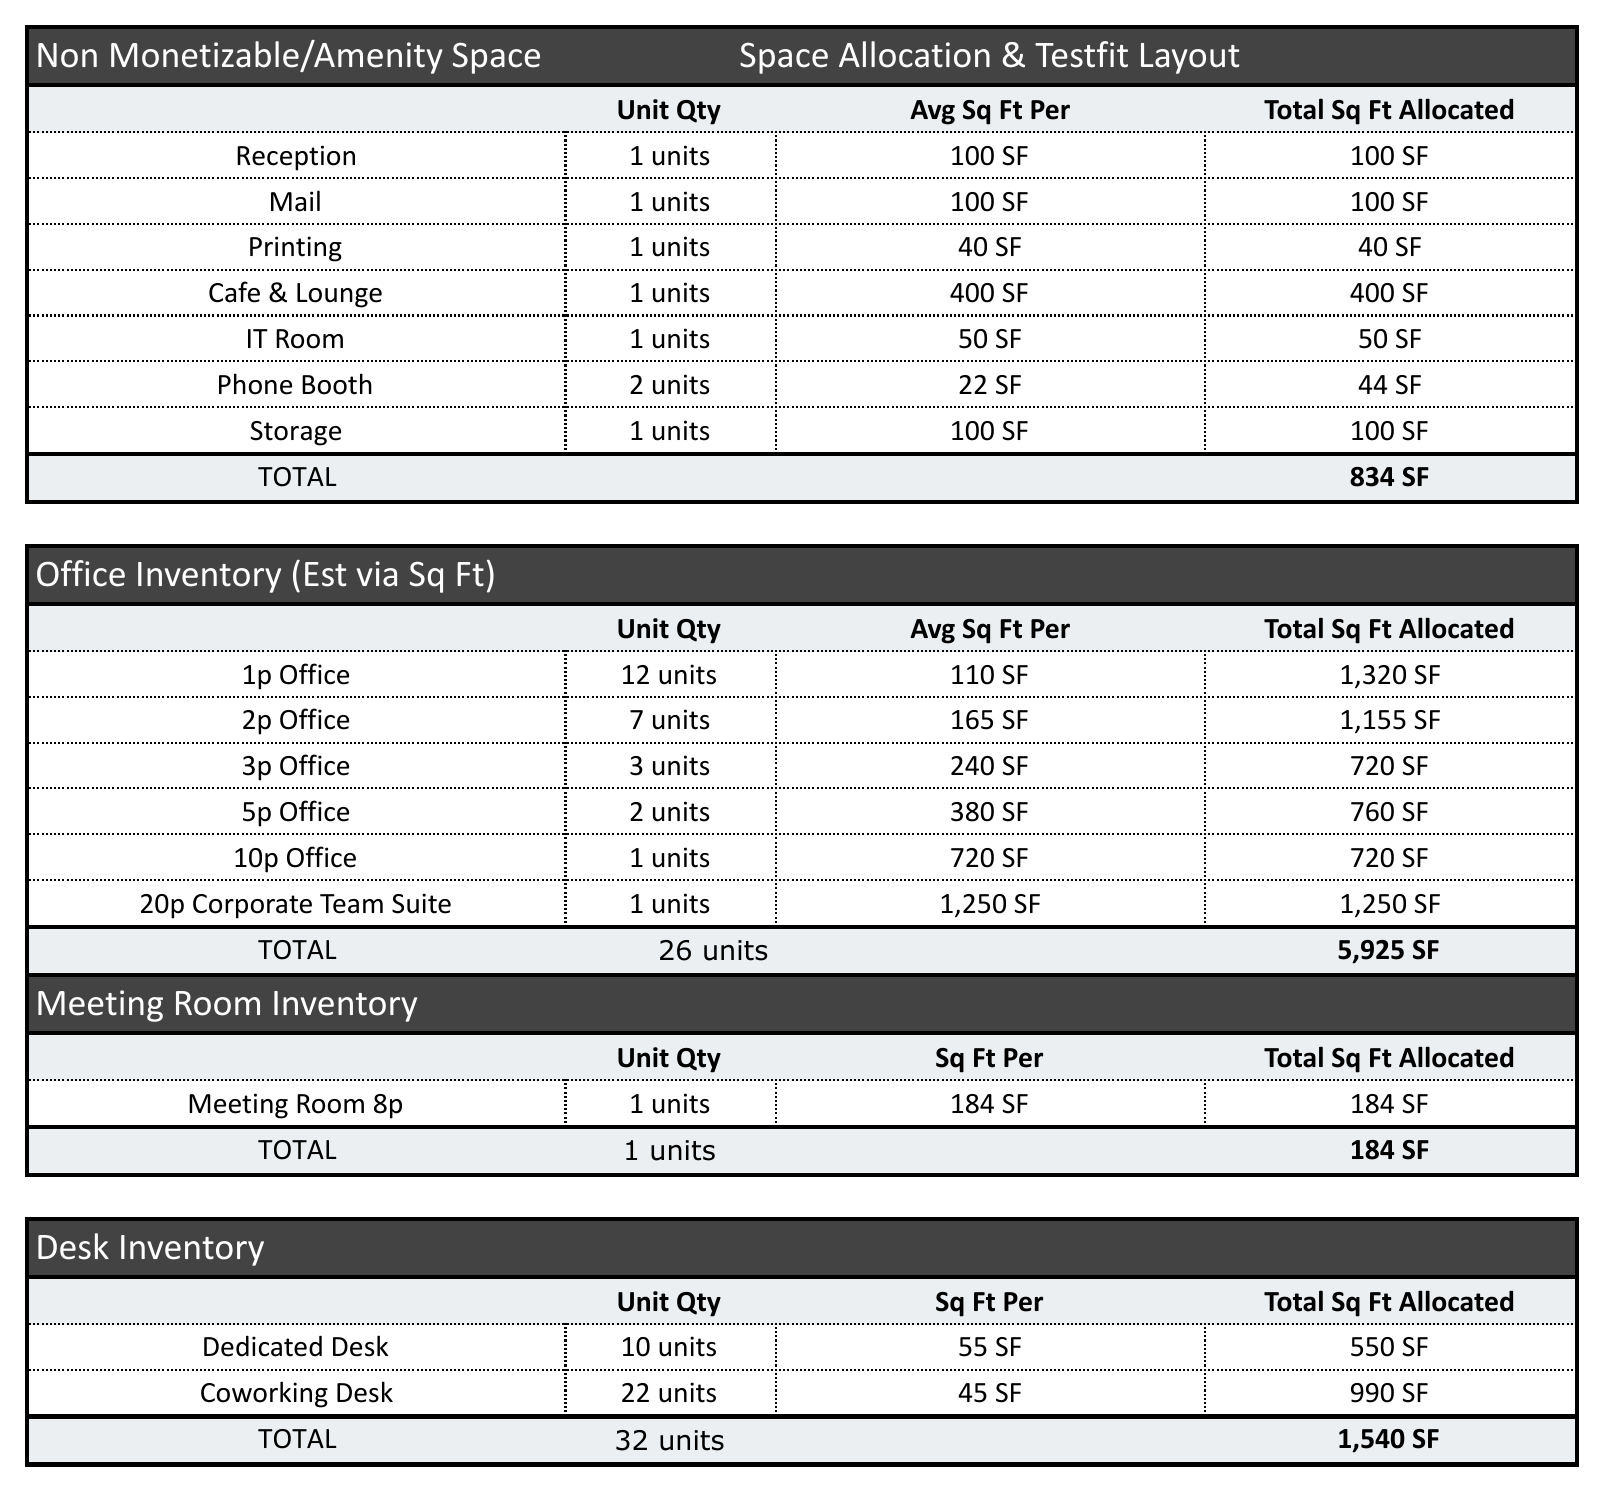
Before any rate is applied, the building has to be divided into rooms. How it divides is a fact about the floor plate, not a preference.
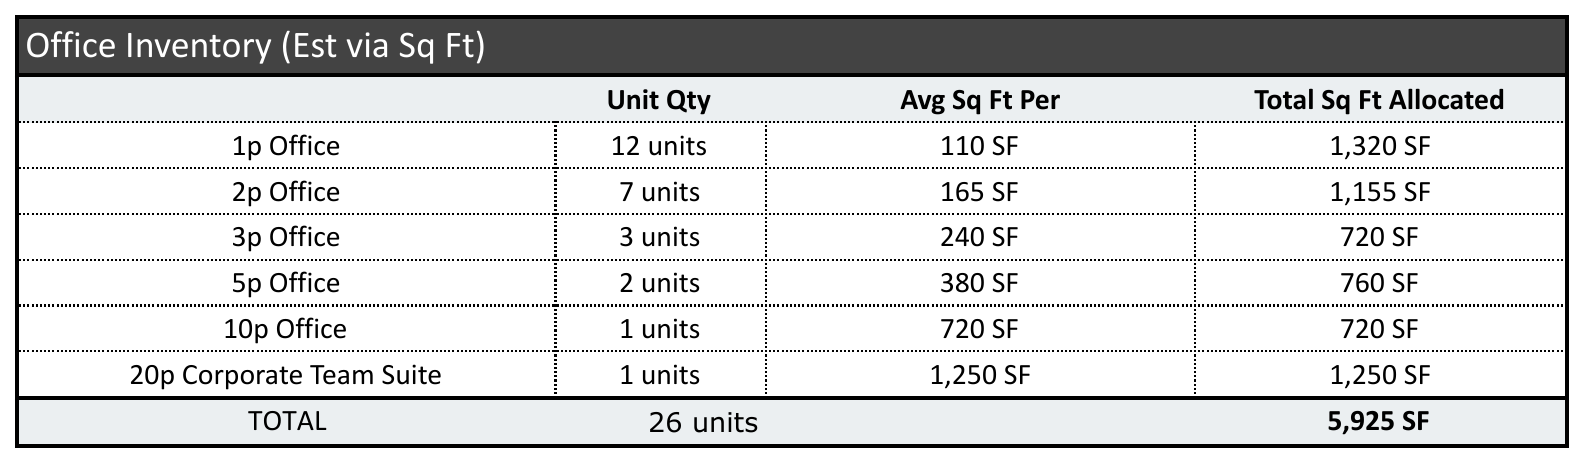
What to look at
How many offices of each size the floor plate yields, and the total square footage they consume against the usable area.
What would worry me
Counts that came from a rule of thumb rather than a drawing. They set the rent roll, which sets the revenue. An assumed count is a revenue line wearing a number.
Check what it charges
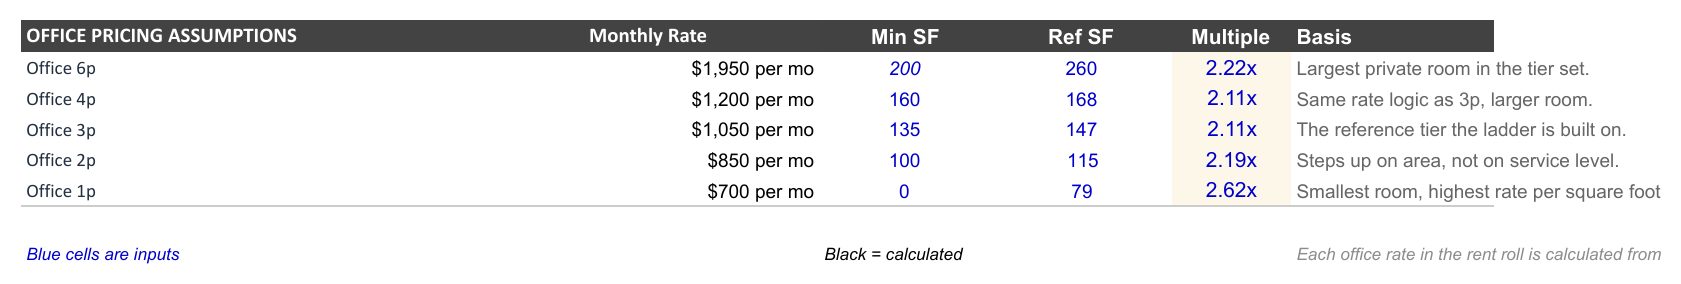
Rates are not guessed one room at a time. They come off market rent through a multiple per unit type.
What to look at
Whether rates step sensibly by unit size, and whether the smallest rooms carry a premium per square foot. They should: the private door carries the cost, not the area.
What would worry me
A flat ladder, or rates carried over from a different building. Four office sizes at the same price means nobody priced them, and it inflates every line below.
Read the rent roll
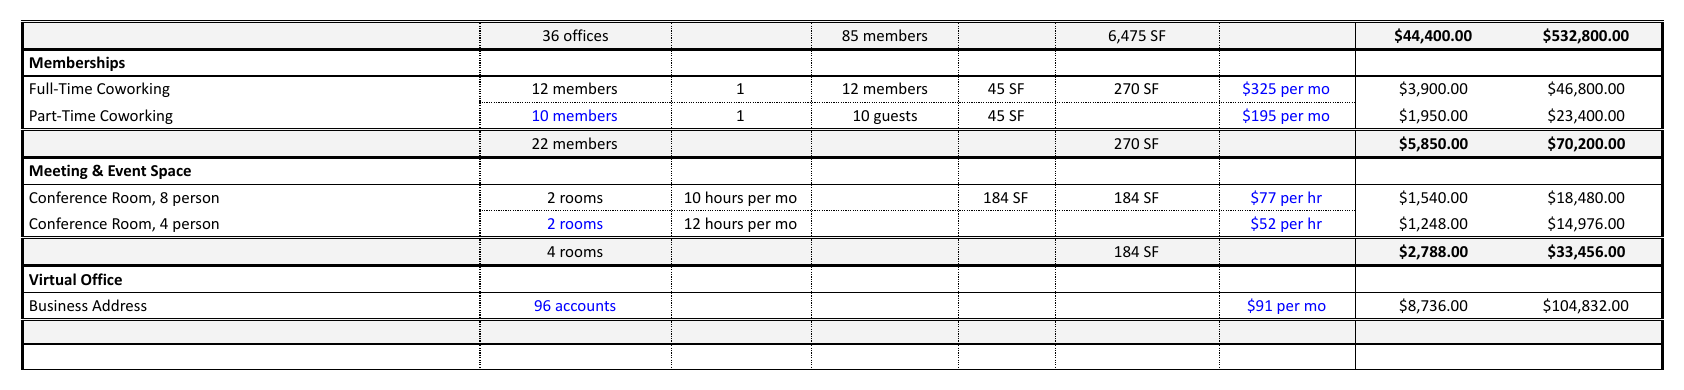
The space at full performance: every unit at its rate, no ramp in it.
What to look at
Unit count and rate on each line. Check the square footage allocated against the usable area from stop two.
What would worry me
Reading it as the forecast. No ramp, no vacancy. This is the ceiling, not next year. Find the month the model says you reach it.
Where the revenue comes from
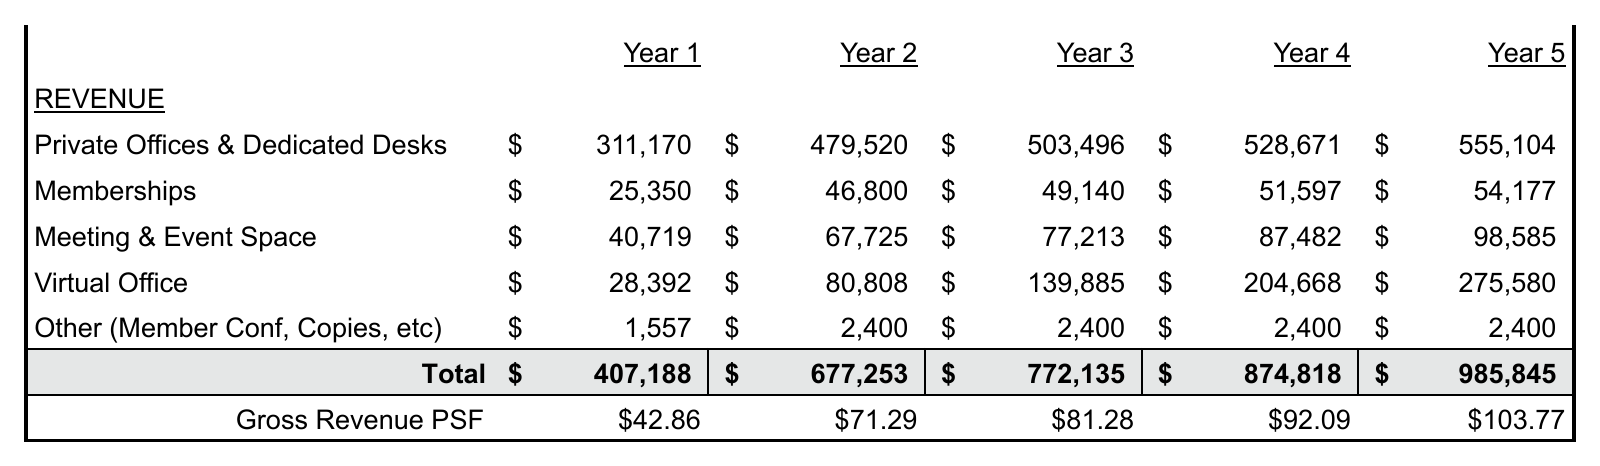
Flex revenue is a stack of separate products, each with its own sales motion.
What to look at
Which line carries the weight. Private offices are the engine and typically hold the majority of stabilized revenue; desks, meeting rooms, virtual office and support services sit around them.
What would worry me
An ancillary line doing too much work. Meeting rooms and memberships are the hardest to sell and the first to disappear.
Open the sixty month engine
Behind the annual columns sits a sixty month grid. The annual figures are sums of it.
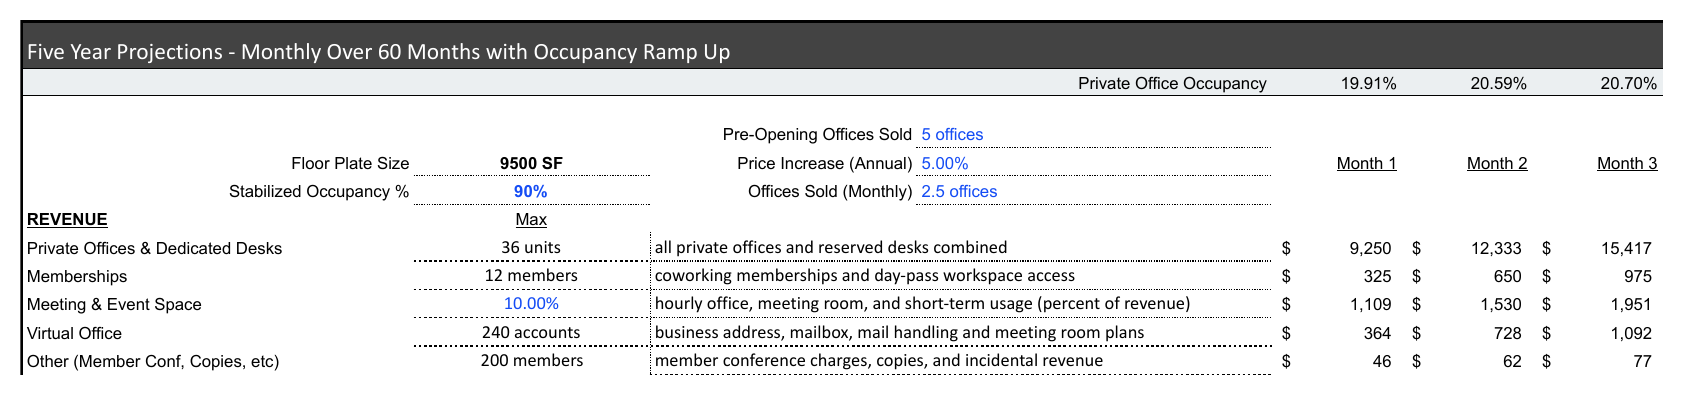
What to look at
The occupancy row across the top, and how long it takes to reach stabilization. Then read down any single month to see what the space earns that month across every stream.
What would worry me
An occupancy row that jumps rather than climbs. Filling a space is a sales motion measured in offices per month, not a curve you can assume. Every annual number above rests on it.
Watch what free rent does
Abatement is a period at the start of the lease with no base rent due. The monthly grid shows exactly what it does.
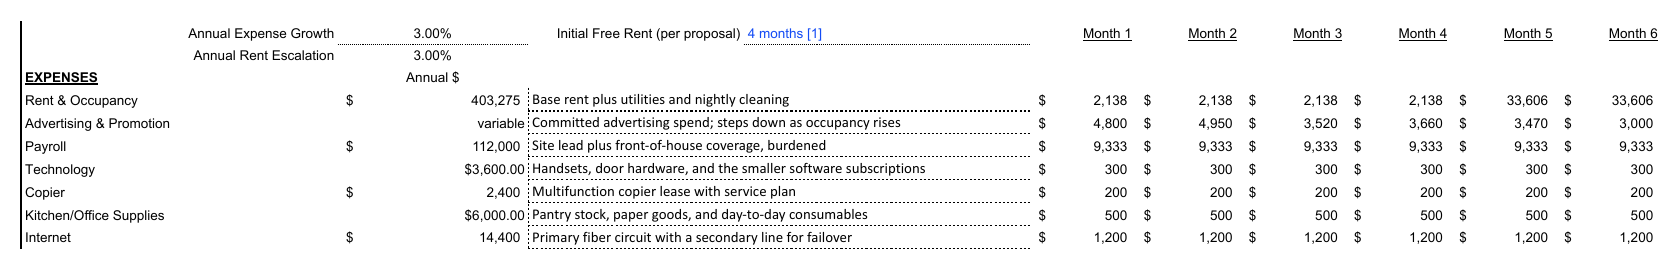
What to look at
Where the rent line steps up. During abatement the model carries only pass-throughs such as utilities and cleaning; the month the full figure appears is the month the clock really starts.
What would worry me
Abatement counted from the wrong date. It begins at possession, and those first months are construction. Six months in a lease can be three months of useful abatement.
Read what it costs to hold the door open
Total occupancy cost is base rent plus every pass-through.
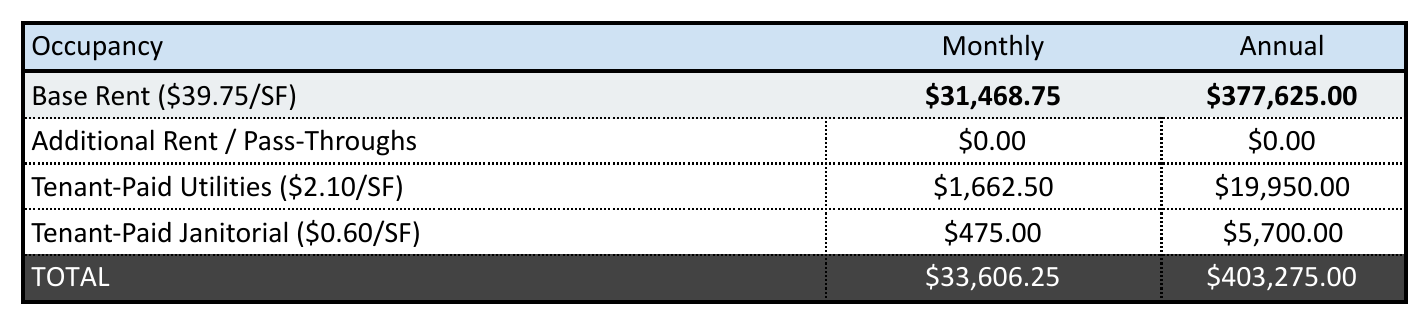
What to look at
The all-in total, not the base rent. Gross rent covers everything; net or NNN means taxes, insurance and common area come on top, often several dollars per square foot.
What would worry me
A pass-through carried at zero, or missing. This is where the unexpected line item hides. If a line says zero, find out whether that is a fact or a placeholder.
Read the full cost stack
Revenue is what the space collects. NOI is what is left after the stack below.
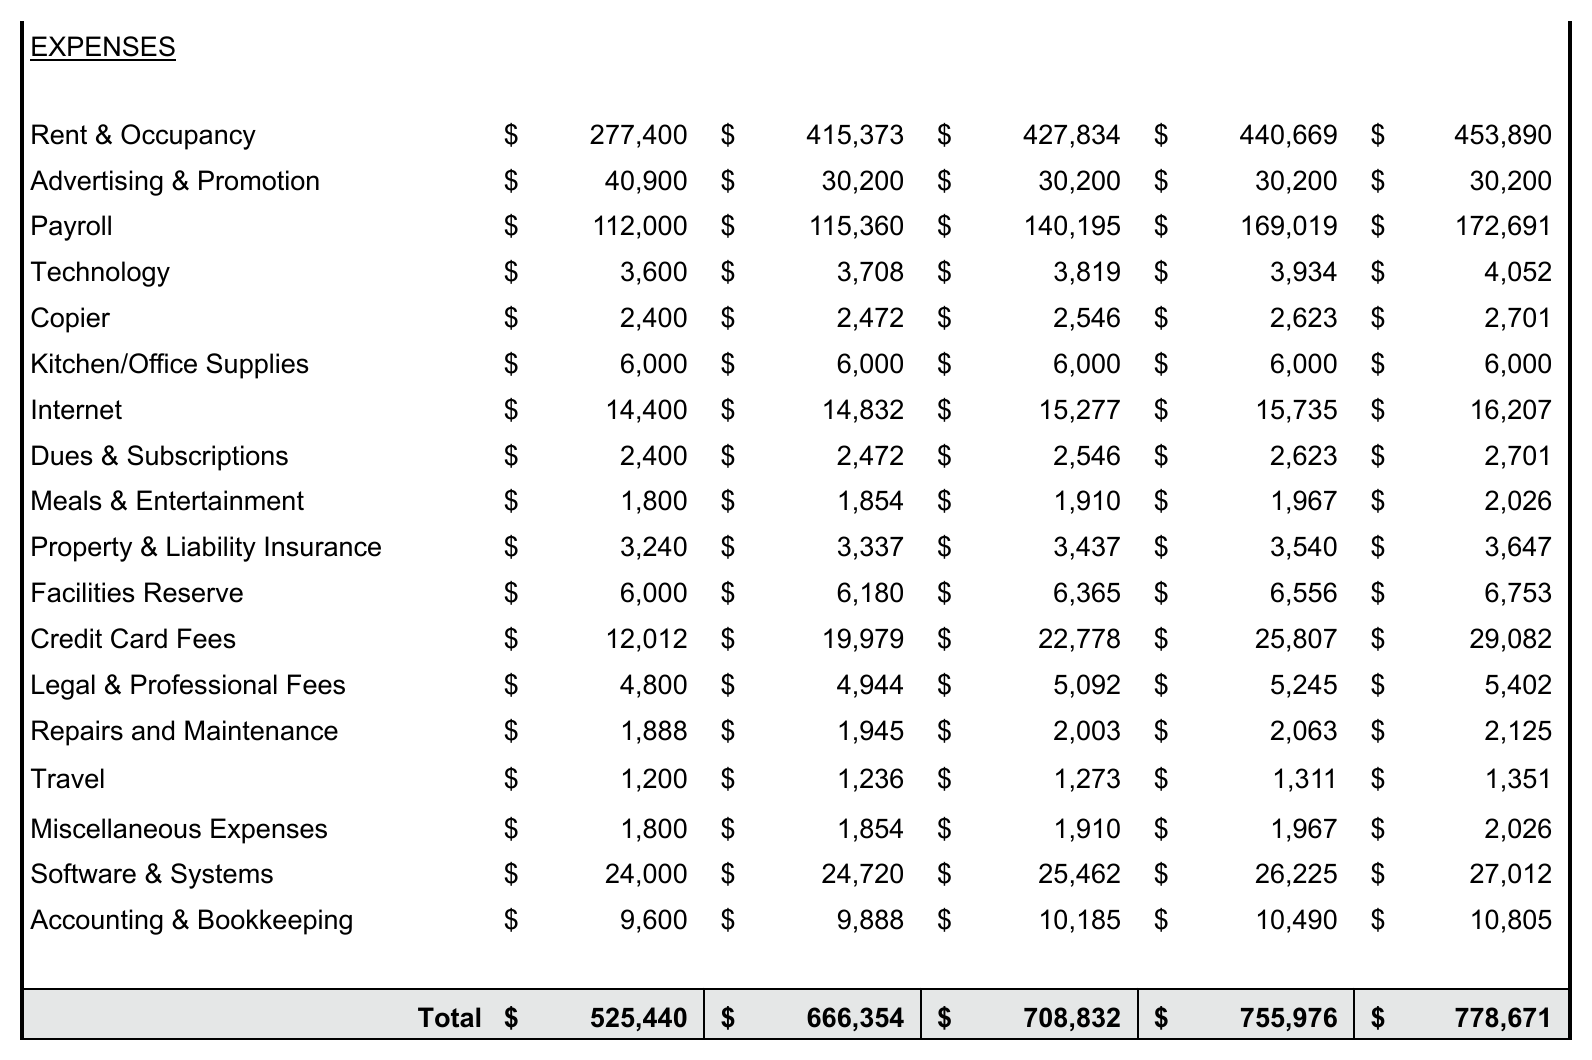
What to look at
Rent as a share of stabilized revenue, and whether payroll matches the staffing the space actually needs. Rent alone often runs around 40 percent.
What would worry me
A stack with no site leader in it, or payroll that would not staff the hours the space is open. Strong revenue still loses money against a heavy stack, and NOI is what a lender reads first.
Find break-even, and read year one for what it costs
Does this building carry itself, and what does it take to get there.
What to look at
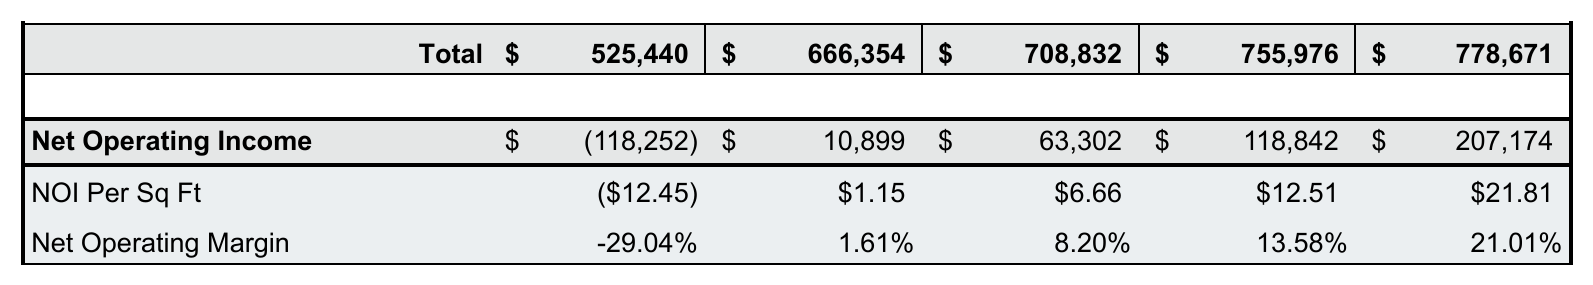
Three numbers. Break-even occupancy: the fill level where revenue covers cost. Break-even month: when the ramp reaches it. Year one loss: the cash consumed before it does.
What would worry me
Reading year one as a verdict rather than a funding requirement. It is negative in almost every flex pro forma, because full rent starts while revenue ramps. It tells you how much cash you need, not whether the deal works.
Then push on what is soft
The numbers worth arguing with carry the most weight with the least evidence behind them.
What to look at
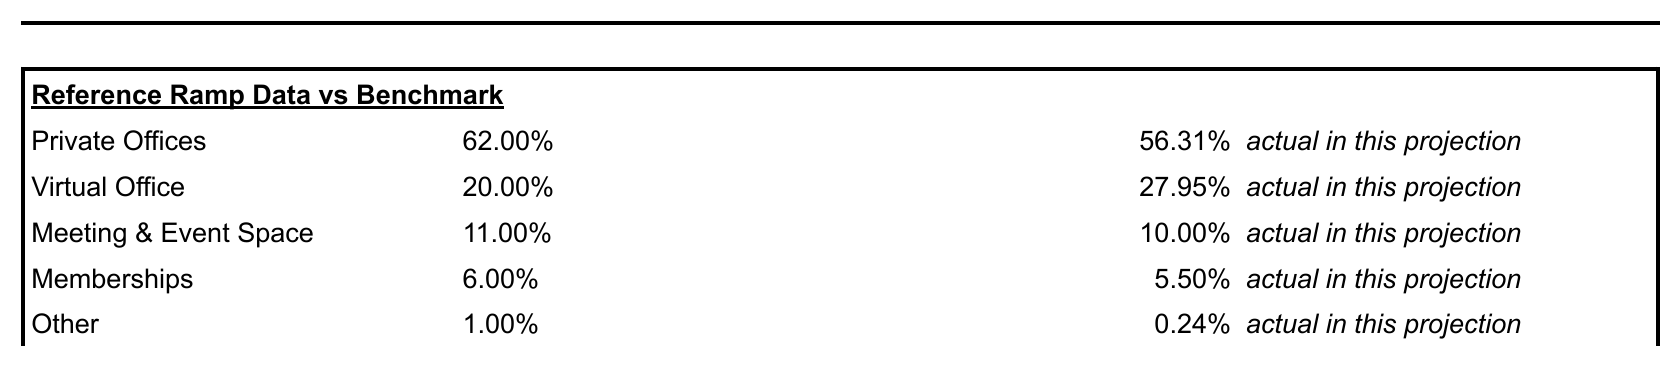
Each stream as a share of the total, against the benchmark. Above it, the model may be leaning on revenue it cannot sell. Below it, revenue may be sitting on the table.
What would worry me
An assumption presented as a fact. Stress the ones that move the outcome most: slower fill, pricing at the bottom of the band, lower stabilized occupancy, shorter abatement. Does it still cover costs at half full?
Keep going
Want this read on your own building?
Bring the address, the floorplate, and the lease terms. What comes back is a model built on those specifics, with every assumption labeled for what it is.
Book a Strategy Call